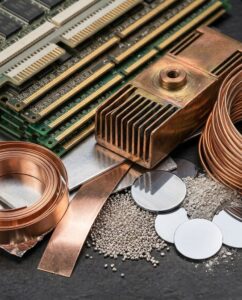


Just a few months ago, metal recyclers were convinced that changes in the automotive market would have a very significant impact on the recycling market, including that for non-ferrous metals (copper, aluminium, nickel, recycling of cables, batteries and electric motors) and rare-earth metals (lithium, cobalt, neodymium, praseodymium, and others). Everyone expected that, in the long term, the electric car market would bring about significant changes to car recycling. Given the metals contained in electric vehicles – and their quantity and value – many companies have begun investing in new technologies, particularly in the field of battery recycling, which would enable the recovery of valuable metals in an environmentally friendly manner.
In the short term, the market anticipated increased demand for non-ferrous metals, a rise in the number of internal combustion engine cars sent for recycling (replacement with electric vehicles), whilst in the long term, a reduction in the recycling of internal combustion engine cars and, consequently, a decline in the amount of recovered aluminium, from which internal combustion engines are made.
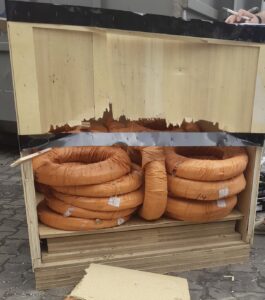
New opportunities have also arisen in connection with the recycling of electric motors, batteries and purchase of copper cables, of which there are far more in electric cars than in petrol and diesel cars.
The expected rise in demand for non-ferrous metals was due to the fact that electric cars use more non-ferrous metals than traditional internal combustion engine vehicles:
According to various analyses and reports, it can be estimated that the value of the metals in an electric car accounts for a significant proportion of its production costs. According to some studies available online, metals may account for as much as up to 40-50% of the production costs of an electric vehicle.
Despite the higher consumption of non-ferrous metals in electric cars (particularly copper), a fall in demand for aluminium and platinum was forecast. Aluminium, due to the phasing out of the production of internal combustion engines and gearboxes, which are largely made of aluminium (aluminium castings), whilst the reduction in demand for platinum was expected to be caused by a decline in the production of catalytic converters, in which platinum is used in large quantities and which are not used in electric cars.
In addition to the above changes relating to electric cars, we can also expect increased demand for non-ferrous metals in connection with the construction of charging points, their connections and the modernisation of the electricity grid to provide the necessary connection capacity (transformers, cables, etc.). The transformation of the automotive market has raised many questions and concerns amongst vehicle recycling companies.
A key change will affect the market for second-hand spare parts, which will have a significant impact on the revenue of vehicle dismantling centres. The powertrain of a vehicle with an internal combustion engine is the best-selling component for virtually all car dismantling companies. The powertrain of an electric vehicle differs significantly from that of a combustion-engine vehicle – it is smaller and lighter, and has far fewer moving parts. Fewer moving parts mean fewer breakdowns – this is good for the consumer, but not good for car recycling companies, which need to sell parts to cover the costs of acquiring, transporting and processing the vehicle.
Car body recycling will also change. Before shredding a car body, the battery will have to be removed from the vehicle. This may be difficult, costly and dangerous, given the need to remove a battery which, if handled incorrectly, could catch fire.
Once the battery has been removed, the question of its recycling remains, and this is currently an unknown. From the perspective of car recycling companies, an electric vehicle is a vehicle based on a built-in battery, and we do not know whether it will be recycled, as its service life is designed to be longer than that of the car in which it is fitted. This has led to the development of a range of programmes for their reuse, for example in energy banks.
As the battery represents the main value of a scrapped electric vehicle, it may well be that battery recycling companies will seek to dominate the car recycling market. These companies will have the expertise required to remove and recycle batteries and other valuable components (electric motors, copper cables) and will deliver the car bodies themselves to steelworks or other end-user recyclers.
At this point, it is also worth mentioning the recycling of road and rail tankers, petrol pumps and fuel depots, the number of which is set to decline in the long term due to reduced demand for fuel. However, I would not expect any sharp increases in this area. I believe that these items will be recycled naturally as they reach the end of their useful life.
Despite the bright future predicted for the industry, we have recently seen a decline in demand for electric cars. This is due to fires in electric cars, their range in winter, and problems with the availability of chargers and insurance cover. As a result, European factories are closing down and an increasing number of countries are beginning to question whether electric cars are a good idea.
For the battery recycling sector, this could mean that investments made in battery recycling will become unprofitable, whilst the recycling market for internal combustion engine vehicles will continue to operate as normal.
In summary, the growth of the electric car market is undoubtedly having an impact on the car recycling sector and the non-ferrous metals market through increased demand, a shift in preferred metals, and the need for innovation in vehicle recycling technology.
Only time will tell what the future holds.