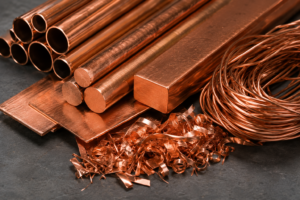


In the fourth quarter of 2025, copper prices reached record levels, exceeding the 10,000-euro-per-tonne mark. Strong demand, limited supply and the growing importance of the energy transition mean that the market is entering 2026 with a clear imbalance. For participants in the physical market – producers, recyclers and trading firms – this means continued price pressure and increased volatility.
Demand for copper
One of the main drivers of growth in demand for copper The energy transition remains a key factor. The development of renewable energy sources, the modernisation of transmission grids and investment in energy storage facilities are driving high demand for copper, which is used in both cables and energy infrastructure components.
Electromobility remains a key area. Electric vehicles consume significantly more copper than vehicles with internal combustion engines, and additional demand is generated by charging infrastructure, public transport and urban regeneration.
Industry and the digitalisation of the economy are also becoming increasingly important. Process automation, the development of data centres and IT infrastructure are driving up copper consumption in electrical installations and cooling systems.
Bearing in mind the above growth factors, one cannot overlook the role of the construction sector, which is currently experiencing a marked slowdown. Residential and infrastructure construction is one of the key sectors for copper, particularly in the areas of electrical installations, transmission networks and technical equipment for buildings.
Should the construction market pick up – driven, amongst other things, by lower borrowing costs and improved access to finance – an additional boost to demand for copper can be expected.
Copper supply
The rate of growth in copper production remains limited. New mining projects require long-term investment, and access to high-quality deposits is becoming increasingly difficult. Furthermore, rising energy costs and increasingly stringent environmental regulations are affecting the profitability of new mining investments.
The supply situation is further exacerbated by unexpected operational disruptions at existing mines. A notable example is the incident at one of the world’s largest copper mines – Grasberg – where technical problems in the underground section of the mine led to a significant reduction in production. This event had a direct impact on global supply forecasts, forcing analysts to revise their expected production volumes for 2025–2026.
Copper recycling and scrap
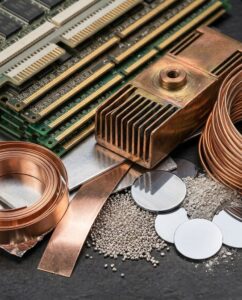
Given the limited growth in production, copper recycling and the trade in copper scrap are playing an increasingly important role. Recycled materials are becoming a key factor in balancing the market, particularly in Europe.
Given the current levels of copper prices on global markets, changes in smelters’ pricing policies regarding annual contracts are to be expected. High prices for primary copper encourage an increase in discounts on recycled copper, which directly affects trading conditions on the scrap market.
At the same time, the high supply of copper scrap in the fourth quarter of 2025, resulting, amongst other things, from the realisation of stocks at record prices, may in the short term lead to a reduction in the availability of scrap in 2026, which will result in increased competition for the raw material and improved pricing terms for suppliers.
Exchange rates
The exchange rate remains a key factor influencing copper prices on the scrap market. Fluctuations in the zloty exchange rate can cause changes in raw material prices at domestic collection points, even when stock market prices remain stable. For the Polish market, this means greater price volatility and the need for ongoing price protection copper at RMC 😊.
Market outlook for 2026
The combination of rising demand and limited supply – both primary and secondary – poses a real risk of a copper deficit in 2026. Even a slight imbalance between production and consumption could result in price pressure, periodic supply shortages and increased market volatility.
Summary
The copper market is entering 2026 in a very challenging and volatile phase. On the one hand, demand for copper is high and continues to rise (in the energy sector, electromobility, industry and, in the future, the construction sector as well). On the other hand, the supply of copper is limited – both from mines and on the scrap market. Added to this are unpredictable events, such as problems at major mines and fluctuations in the zloty exchange rate.
For scrap metal companies, this means one thing: prices can fluctuate significantly, and attempts to „wait for an even better price” carry a real risk.
All you need to do is:
– changes in exchange rates,
– a price correction on the stock market,
- a greater supply of scrap metal at any given time,
so that the purchase price falls more quickly than we expect.
That is why it is not worth speculating and holding on to copper indefinitely, hoping for further price rises. Such a strategy often results in a loss rather than a profit.
The safest option in the current circumstances is:
– ongoing sales of copper to RMC 😊,
– maintaining prices at current levels,
– regular stock rotation rather than holding stock and risking a drop in value.
RMC offers stable terms of cooperation, market-based prices and the opportunity to hedge the value of copper on an ongoing basis. In times of high volatility, it is better to have a guaranteed price today than to rely on an uncertain tomorrow.
Sell copper on an ongoing basis to RMC and safeguard your margin – rather than risking a loss.
Ministry of Culture and Ministry of the Interior